Ensuring Uninterrupted Commercial Logistics Across India
Physical transportation of commercial goods represents the lifeblood of domestic supply chains across India. To prevent tax evasion and eliminate physical transit checkpoints, the Goods and Services Tax Council instituted the Electronic Way Bill (E-Way Bill) mechanism under Rule 138 of the CGST Rules. Any commercial consignment exceeding statutory value thresholds must be accompanied by an authenticated electronic transit slip generated from the central government portal.
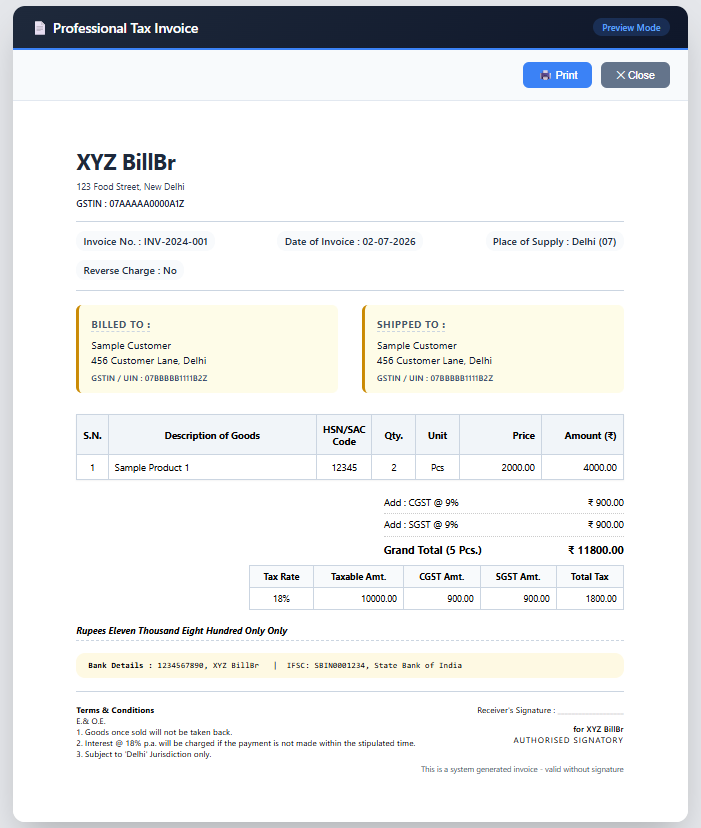
Transporting freight without a valid, active e-way bill can lead to catastrophic consequences, including the physical seizure of commercial vehicles and punitive monetary penalties. Using an integrated platform like the sales invoice generator ensures outward bills contain all mandatory transit data fields for seamless e-way bill generation.
Core Regulatory Architecture: Threshold Limits and Structure
Under federal GST regulations, generating an e-way bill is mandatory for any interstate movement of goods where the consignment value exceeds fifty thousand rupees. Consignment value is legally defined as the aggregate invoice amount inclusive of all applicable central, state, or integrated taxes, but excluding exempt supplies.
For intrastate transportation within state boundaries, individual state governments retain the authority to set higher thresholds. For instance, states such as Maharashtra, Delhi, and West Bengal have elevated intrastate e-way bill limits to one lakh rupees, reducing compliance burdens for local commercial distributions.
| Regulatory Dimension | Interstate Transport Rules | Intrastate Transport Rules | Statutory Enforcement Mechanism |
|---|---|---|---|
| Mandatory Threshold Limit | Consignment value exceeding Rs 50,000 | Rs 50,000 to Rs 1,00,000 (state specific) | Strict highway mobile squad inspections |
| Part A Data Requirement | Supplier/recipient GSTIN, HSN, invoice details | Supplier/recipient GSTIN, HSN, invoice details | Locks consignment details on central portal |
| Part B Data Requirement | Vehicle registration number / Transporter ID | Vehicle registration number / Transporter ID | Validates active physical transport authorization |
| Consignment Validity Duration | 1 day per 200 km (standard cargo) | 1 day per 200 km (standard cargo) | Consignment becomes illegal upon time expiration |
Step-by-Step Procedure to Generate and Manage E-Way Bills
Prior to goods dispatch, create your authenticated tax bill using our GST invoice generator. Log into the official e-way bill portal (ewaybillgst.gov.in) and enter the invoice number, date, consignee shipping address, and six-digit HSN codes. This completes Part A generation.
Next, enter the vehicle registration number or assign the shipment to a registered third-party logistics transporter ID to complete Part B. If goods transfer to a secondary vehicle during transit due to mechanical failure, the transporter must update vehicle details on the portal prior to resuming transit.
Draconian Penalties Under Section 129 and Section 130
Under Section 129 of the CGST Act, transporting goods without a valid e-way bill results in the immediate detention of the vehicle and cargo, carrying a mandatory penalty equal to 200 percent of the applicable tax liability. If intentional tax evasion is proven, Section 130 permits full confiscation of the underlying goods and transport vehicle.
Vehicle Breakdown Procedures and Part B Extension Norms
During highway transit, commercial goods vehicles are subject to dynamic inspection by state tax enforcement squads under Section 68 of the CGST Act. If a transport truck breaks down or suffers unexpected logistics delays, the transporter or supplier must log into the E-Way Bill portal to update vehicle registration details in Part B or extend the bill validity window within eight hours prior to expiry.
Transporting consignments with an expired E-Way Bill is treated as an intentional tax evasion attempt under Section 129, resulting in vehicle detention and heavy financial penalties equal to two hundred percent of the tax payable on the transported goods.
Frequently Asked Questions
Is an e-way bill required for transporting exempt goods?
No, goods specifically listed in Annexure to Rule 138(14), such as unprocessed agricultural produce, fresh milk, and raw food grains, are completely exempt from e-way bill requirements regardless of consignment value.
Can an expired e-way bill validity period be extended?
Yes, transporters can extend validity on the portal within eight hours before or eight hours after the original expiration timestamp, provided delay reasons such as vehicular accidents or transit bottlenecks are recorded.
Is an e-way bill mandatory for transporting goods on job work?
Yes, interstate movement of goods sent for job work requires an e-way bill generated either by the principal manufacturer or registered job worker, irrespective of whether the consignment value exceeds Rs 50,000.
Is an E-Way Bill required when transporting goods solely by rail or air freight?
Yes, for railway, air, and ocean transport, an E-Way Bill must be generated by the supplier or recipient, and Part B must be updated with the Railway Receipt (RR) number, Airway Bill number, or Bill of Lading prior to delivery.
Airtight transportation compliance ensures seamless delivery schedules and protects your enterprise from heavy statutory fines. Generate compliant invoices with complete transit data fields using the Billbr Invoicing System today.
Falcon HQ
falcon.hq@gmail.com