Managing Commercial Adjustments and Sales Returns Post-Invoicing
In dynamic commercial trade, business transactions rarely conclude without post-sale adjustments. Customers return defective merchandise, negotiated post-sale volume rebates are granted, clerical errors in unit pricing are discovered, or agreed project deliverable scopes are revised. Once a formal GST tax invoice has been issued and uploaded to the government portal, the law strictly prohibits deleting, erasing, or arbitrarily altering the historical document.
To adjust taxable values and output tax liabilities legally, suppliers must issue formal statutory instruments: Credit Notes and Debit Notes under Section 34 of the CGST Act. Utilizing our verified GST invoice generator allows commercial enterprises to issue compliant credit and debit notes mapped directly to original sales invoices.
Statutory Mechanisms: Section 34 and Annual Time Limits
Under Section 34(1) of the CGST Act, a supplier issues a Credit Note when the taxable value or tax charged on the original invoice exceeds the actual liability, or where goods supplied are returned by the recipient, or where services are found deficient. Issuing a credit note reduces the supplier output tax liability and requires the recipient to reverse corresponding Input Tax Credit.
Conversely, under Section 34(3), a Debit Note is issued when the taxable value or tax charged in the original invoice is found to be less than the true liability, effectively increasing the supplier tax liability. Crucially, under amended Section 34(2), a Credit Note for any financial year must be declared in GSTR-1 on or before the 30th day of November following the end of the fiscal year, or the date of furnishing the annual return, whichever is earlier.
| Document Type | Permissible Commercial Trigger | Tax Liability Impact | Statutory Cutoff Deadline |
|---|---|---|---|
| Credit Note (Sec 34(1)) | Sales returns, price reductions, post-sale rebates | Reduces supplier output tax liability | Strictly November 30 following fiscal year end |
| Debit Note (Sec 34(3)) | Undercharged price, upward scope expansion | Increases supplier output tax liability | No restrictive statutory cutoff date |
| Financial / Commercial Note | Discounts not satisfying Section 15(3) rules | Zero tax adjustment (book entry only) | Can be issued at any time for accounting |
| Recipient Debit Note | Buyer internal accounting sales return voucher | No direct tax portal adjustment | Supplier must issue credit note for portal sync |
Step-by-Step Procedure to Issue Compliant Credit and Debit Notes
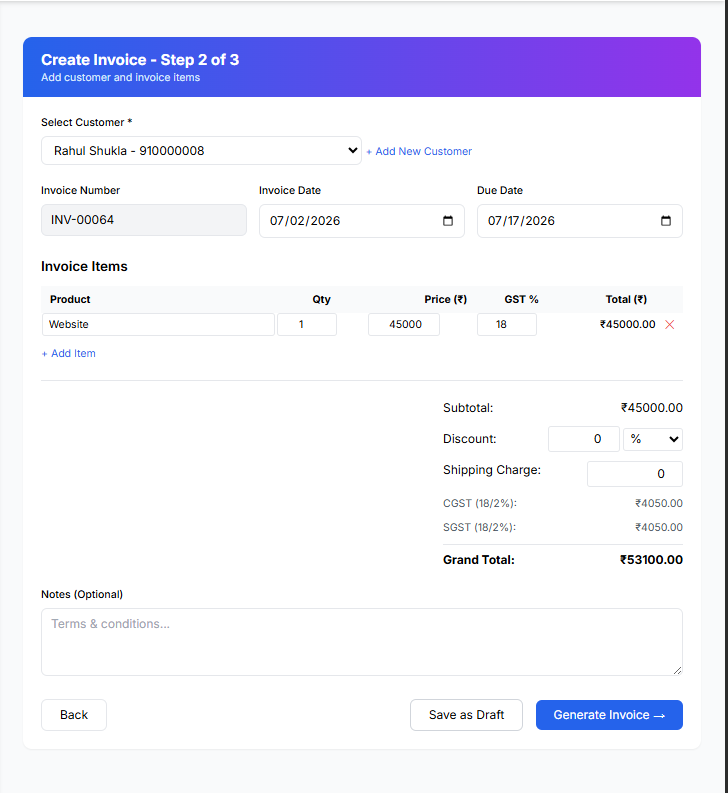
To issue an authenticated adjustment note, open our GST adjustment generator and choose "Credit Note" or "Debit Note". Reference the original invoice number, issuance date, and customer verified 15-digit GSTIN.
Specify the differential taxable amount, applicable HSN codes, and corresponding tax rate splits. The platform generates an authenticated document with unique sequential numbering. Report the document in Table 9B of your monthly GSTR-1 return to adjust output liabilities.
Critical Pitfalls in Credit Note Issuance
Attempting to issue tax credit notes after the November 30 annual deadline violates statutory guidelines, forfeiting the supplier right to reduce output tax liability and forcing the business to absorb the tax loss.
Section 34 Cutoff Deadlines and Output Tax Reversals
Issuing Credit Notes and Debit Notes under Section 34 allows businesses to legally adjust outward sales liabilities without altering previously filed invoices. A Credit Note is issued when goods are returned, services are deficient, or post-sale discounts are granted, allowing the seller to reduce output tax liability.
Crucially, Section 34(2) establishes a strict statutory time limit: credit notes for any financial year must be declared on or before November 30th following the end of the financial year, or the date of filing the annual return, whichever is earlier. Failing to report credit notes before this deadline forfeits the right to adjust output tax.
Frequently Asked Questions
Can a single credit note link to multiple original invoices?
Yes, following GST legislative amendments, suppliers can legally issue a consolidated credit or debit note linking to multiple original tax invoices.
Can credit notes be issued without adjusting GST tax amounts?
Yes, commercial or financial credit notes can be issued to adjust commercial ledger balances without adjusting GST, provided Input Tax Credit is not impacted.
Does a debit note require the recipient agreement?
While debit notes represent supplier tax demands, commercial contract terms must support the upward price adjustment to ensure buyer payment.
When should a supplier issue a Debit Note instead of an invoice amendment?
A Debit Note is issued when the taxable value or tax charged in the original invoice is found to be less than the actual value, allowing the seller to collect the differential tax and pass ITC to the buyer.
Mastering credit and debit note workflows protects your business from tax overpayment and maintains pristine ledger hygiene. Generate compliant adjustment notes today with Billbr GST Invoicing Tools.
Falcon HQ
falcon.hq@gmail.com