Navigating Taxable Thresholds in the Indian Education Sector
Education holds an esteemed cultural and constitutional standing in Indian society, traditionally viewed as a non-commercial public service. Under fiscal taxation statutes, recognized formal education receives extensive statutory exemptions to maintain universal access. However, the commercial explosion of private competitive examination coaching academies, test-preparation institutes, skill development centers, and edtech platforms has created a sharp regulatory bifurcation.
While formal schooling remains tax-exempt, commercial private coaching is fully subject to standard indirect taxation. Educational administrators and coaching institute directors must understand the legal boundaries separating exempt education from taxable coaching. Utilizing our payment receipt generator allows institutions to format compliant fee receipts and manage tuition billing seamlessly.
Statutory Architecture: Entry 66 of Notification 12/2017 vs Private Coaching
Under Entry 66 of Notification No. 12/2017-Central Tax (Rate), services provided by an "educational institution" to its students, faculty, and staff are completely exempt from GST. An educational institution is legally defined as an entity providing: pre-school education and education up to higher secondary school; education as part of a curriculum for obtaining a qualification recognized by any Indian law; or approved vocational education.
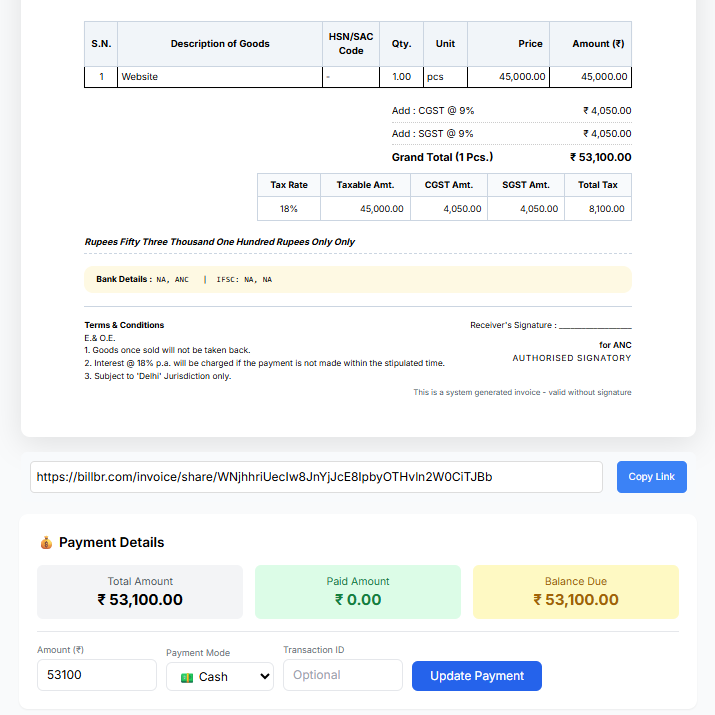
Crucially, private commercial coaching institutes, test-prep academies (for IIT-JEE, NEET, UPSC, etc.), and hobby classes do not grant degrees recognized by law. Consequently, private coaching services are classified under Services Accounting Code (SAC) 999293 and are fully taxable at standard 18 percent GST (9% CGST plus 9% SGST).
| Educational Institution Type | Statutory GST Status | SAC Classification | Invoicing Documentation Rule |
|---|---|---|---|
| Formal K-12 Schools & Colleges | 100% Exempt (Entry 66) | SAC 999211 / 999221 | Standard non-tax school tuition fee receipt |
| Private Competitive Coaching Classes | Taxable at 18% GST | SAC 999293 (Commercial Training) | Mandatory GST tax invoice with 18% tax split |
| Degree Colleges (UGC Recognized) | 100% Exempt (Entry 66) | SAC 999241 (Higher Education) | Exempt tuition receipt for accredited degree |
| Corporate Professional Training | Taxable at 18% GST | SAC 998311 (Management Training) | Full B2B tax invoice with corporate GSTIN |
Step-by-Step Procedure to Generate Tuition Fee Receipts
To generate compliant fee receipts, open our fee receipt generator. Input your institution legal name, campus facility address, and contact credentials. Enter student enrollment identifiers and enrolled academic batch details.
Itemize fee components (e.g., Tuition Fee, Laboratory Charges, Library Access). For commercial coaching academies exceeding the twenty lakh registration threshold, apply 18 percent GST. Download a branded PDF receipt displaying authorized signatures and deliver it to parents via WhatsApp or email.
Common Compliance Errors in Educational Billing
A frequent compliance breach is private coaching academies operating under the guise of charitable trusts claiming educational exemptions under Entry 66. Tax authorities routinely scrutinize coaching revenues, demanding back taxes with compounding interest.
Commercial Coaching vs Formal Education Exemption Boundaries
Navigating indirect taxation for educational institutions requires recognizing the clear statutory boundary between formal education and commercial training. While formal school education and recognized university degrees leading to statutory qualifications are exempt from GST under Entry 66, private coaching centers and test-preparation institutes attract 18 percent GST under SAC 999293.
Fee receipts issued to students and parents must itemize tuition fees, course material books (which may carry lower or nil tax slabs), and exam portal access charges. Providing structured payment receipts with digital UPI payment options reassures parents and maintains transparent institutional accounts.
Frequently Asked Questions
Can parents claim income tax deductions using school tuition fee receipts?
Yes, salaried parents can claim deductions under Section 80C of the Income Tax Act for tuition fees paid for up to two children attending full-time formal schools or universities in India.
Are school bus transportation and catering services exempt from GST?
Under Entry 66, catering, security, housekeeping, and student transportation services provided to pre-schools and schools up to higher secondary are completely exempt from GST.
Do coaching centers need to issue tax invoices to students?
Yes, registered coaching academies supplying taxable training to students must issue formal tax invoices or compliant fee receipts under Rule 46 of the CGST Rules.
Can coaching institutes claim Input Tax Credit on classroom lease rentals and laptops?
Yes, commercial coaching centers paying 18 percent GST are fully entitled to claim Input Tax Credit on classroom lease rentals, IT hardware, air conditioners, and study material printing.
Delivering professional fee receipts builds institutional trust and ensures complete adherence to educational tax regulations. Streamline your academic billing today with Billbr Fee Receipt Solutions.
By deploying specialized cloud billing infrastructure for coaching class and school fee receipt generator: exemption vs 18% gst applicable, Indian commercial enterprises, consultants, healthcare providers, and retailers systematically eliminate manual calculation blunders, maintain transparent books of accounts, and uphold rigorous statutory compliance under prevailing indirect tax laws. Implementing automated billing with verified digital tools like Payment Receipt Generator accelerates customer payment realizations, simplifies annual audit reconciliations, and preserves an.
Falcon HQ
falcon.hq@gmail.com